Companies & Equity
Company and equity research on listed businesses: financial performance, peer comparison, credit quality and valuation.
Lead publication
The newest research from Empire Capital's companies & equity desk.
 Featured research
BSRM Steels Leads Q4 Earnings Momentum While BSRM Ltd Maintains Strong Annual Growth
BSRMSTEEL delivered the stronger Q4 earnings momentum, with implied EPS rising 18.74% q/q and 62.15% y/y to Tk 7.54. BSRMLTD’s implied Q4 EPS reached Tk 8.00, up 27.80% y/y but down 8.57% q/q. Both companies reported higher FY26 revenue, EPS and proposed cash dividends, while BSRMSTEEL showed the stronger earnings acceleration.
Read the publicationMore from Companies & Equity
 01
BRAC Bank PLC: Integrated Equity Research | FY2026–FY2028 Profitability Outlook
BRAC Bank PLC delivered strong H1 2026 results, with consolidated profit after tax reaching Tk 1,423 crore, up 57% year-on-year, and consolidated EPS of Tk 5.07. However, maintaining this momentum may prove challenging as regulatory lending-spread restrictions, treasury-income normalization and credit costs shape future profitability. Empire Capital Research projects consolidated profits of Tk 2,681 crore in 2026, Tk 2,698 crore in 2027 and Tk 2,748 crore in 2028 under its base-case assumptions. This integrated research report examines financial performance, earnings sensitivities, valuation, foreign ownership trends and the potential opportunities and governance risks surrounding the proposed bKash Digital Bank. Our conditional analytical assessment remains HOLD / NEUTRAL.
 02
Apex Foods Limited (APEXFOODS), Equity Research Report
Apex Foods Limited (APEXFOODS) surged 19.58% to Tk 311.50 on 5 October 2026 following the release of its FY2025-26 results, which showed EPS of Tk 14.21 versus Tk 6.41 in the previous year, while the company maintained a 20% cash dividend. Empire Capital Research examines whether the earnings improvement and price breakout represent a sustainable rerating. The report reviews five-year financial performance, earnings quality, cash flow, valuation, technical structure, shareholder positioning and the company's exposure to Apex Spinning & Knitting Mills. Despite stronger momentum, key considerations include the concentration of FY2025-26 earnings in the fourth quarter, dependence of reported NAV on listed investments, low capacity utilization and liquidity risk.
 03
BEXIMCO after the floor: Price discovery, liquidity and the technical map
A research-led review of the post-floor reset, unusual volume and the support-resistance structure shaping near-term risk.
 04
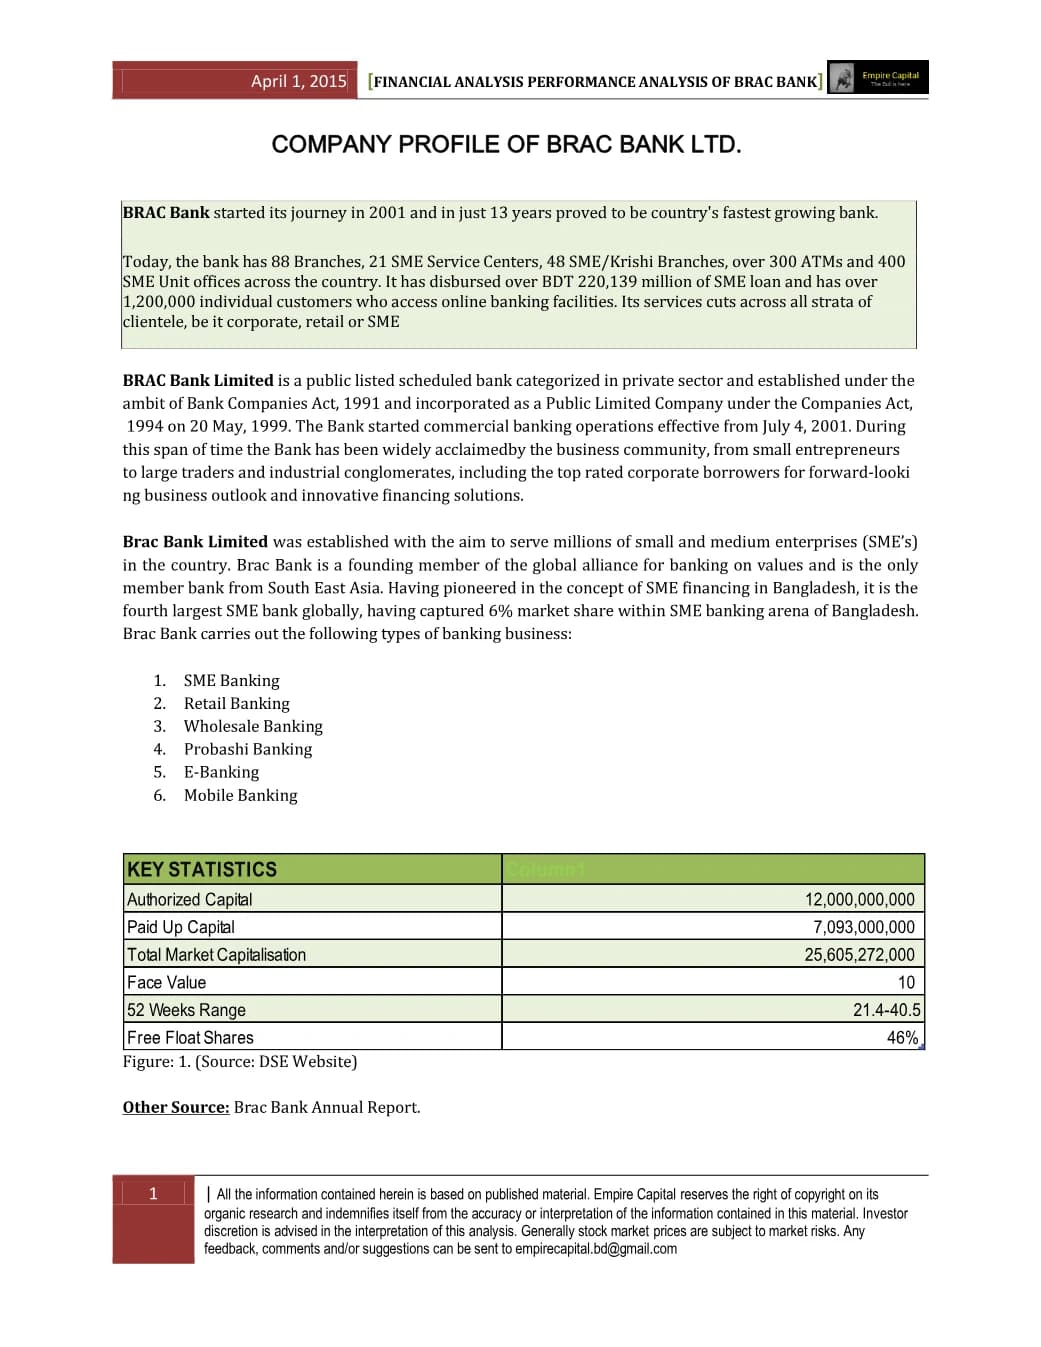
BRAC Bank — 2014 Performance Analysis
A full-year review of BRAC Bank's 2014 financials against 2011–13, its standing versus 29 industry peers, credit quality, large-borrower exposure, its listed stock market portfolio, and the performance of its bKash and BRAC EPL Investments subsidiaries.
 05
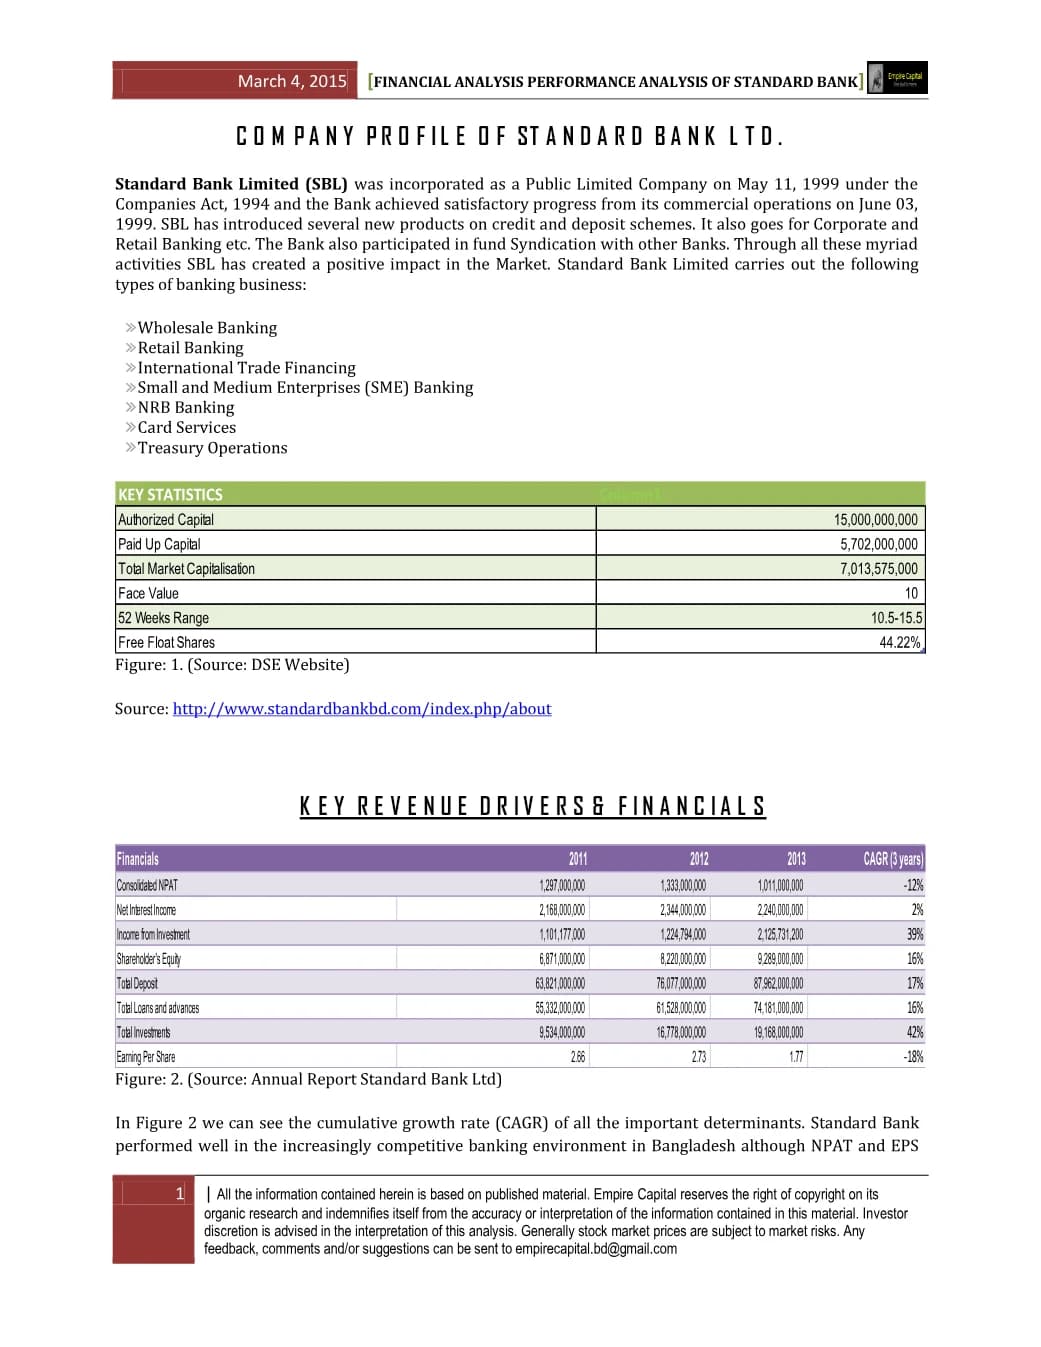
Standard Bank — 2014 Performance Analysis
A review of Standard Bank's 2011–13 financials, a 2014 EPS projection built from Q3 2014 disclosures, its standing versus 29 industry peers and three regional banks, credit quality, large-borrower exposure and a summary of 2014 sponsor share transactions.
 06
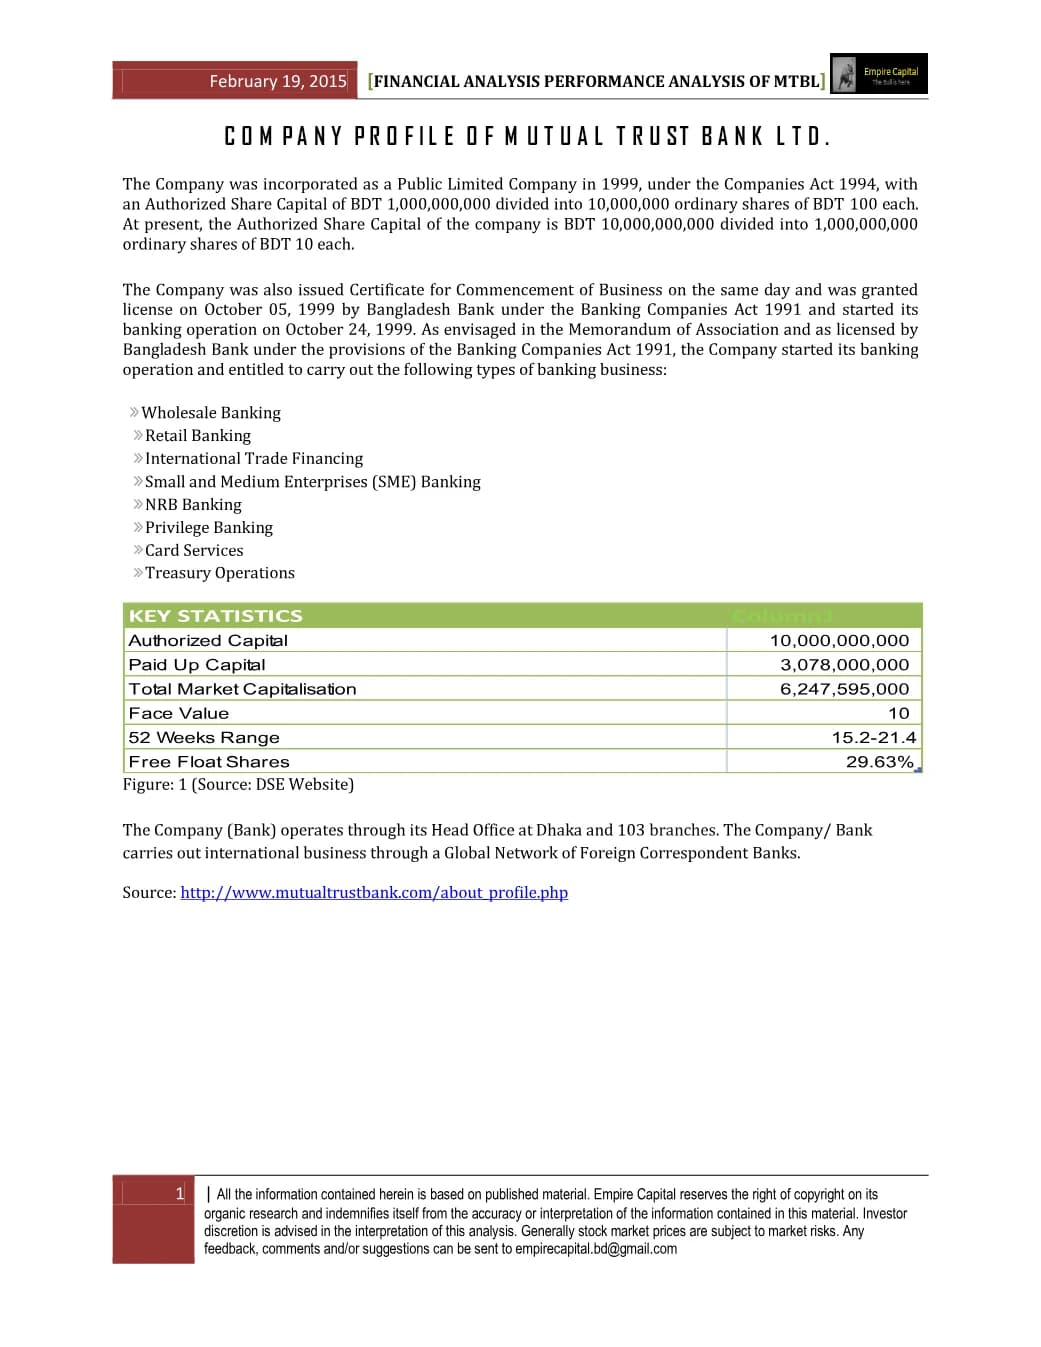
Mutual Trust Bank — 2014 Performance Analysis
A review of MTB's 2011–13 financials, a 2014 EPS projection of Tk 3.13 built from Q3 disclosures (against the Tk 3.12 the bank later reported), its standing versus 29 industry peers and four regional banks, and a full annexure of its capital market exposure.
 07
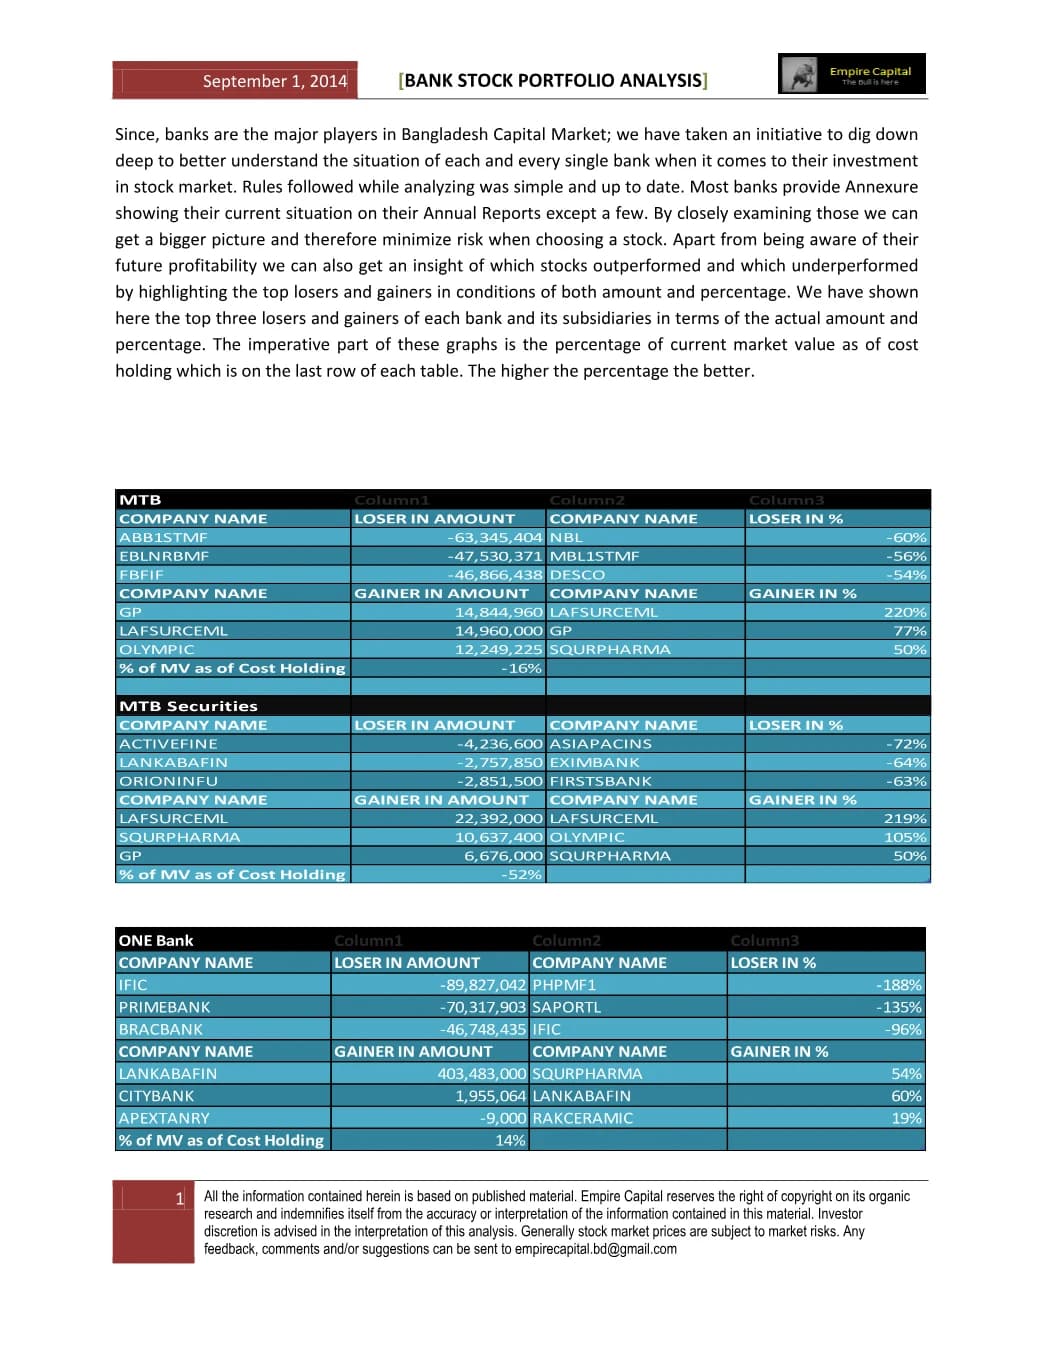
Bank Stock Portfolio Analysis
A bank-by-bank survey of stock market investment portfolios disclosed in annual report annexures: the top three losers and gainers by amount and by percentage for each bank and its brokerage/investment subsidiaries, alongside the market-value-to-cost-holding ratio that summarises overall portfolio health.
Looking for a specific market, company or theme?
Search the complete archive across every Empire Capital research desk.
Search all research