BRAC Bank PLC delivered strong H1 2026 results, with consolidated profit after tax reaching Tk 1,423 crore, up 57% year-on-year, and consolidated EPS of Tk 5.07. However, maintaining this momentum may prove challenging as regulatory lending-spread restrictions, treasury-income normalization and credit costs shape future profitability. Empire Capital Research projects consolidated profits of Tk 2,681 crore in 2026, Tk 2,698 crore in 2027 and Tk 2,748 crore in 2028 under its base-case assumptions. This integrated research report examines financial performance, earnings sensitivities, valuation, foreign ownership trends and the potential opportunities and governance risks surrounding the proposed bKash Digital Bank. Our conditional analytical assessment remains HOLD / NEUTRAL.
INSTITUTIONAL EQUITY RESEARCH
BRAC BANK PLC
INTEGRATED EQUITY NOTE | FY2026–FY2028 PROFITABILITY OUTLOOK
H1 2026 earnings • 4pp lending–deposit spread cap • DSE index scenarios • bKash digital bank
DSE: BRACBANK | Reference price Tk 66.40 as of 8 October 2026 | Research date: 10 October 2026
ISSUER FACTS | 2026E MODEL | 2027E–2028E |
H1 group PAT: Tk 1,423 Cr | 2026E group PAT: Tk 2,681 Cr | 2027E PAT: Tk 2,698 Cr |
H1 EPS: Tk 5.07 | 2026E parent EPS: Tk 9.55 | 2028E PAT: Tk 2,748 Cr |
H1 NPL: 2.03% | Eligible spread capped at 4pp | Digital-bank earnings: excluded |
Prepared for institutional investors, analysts, portfolio managers, fund managers, research teams and senior management.
Analytical research rating: HOLD / NEUTRAL (12–18 months, dated 8 October 2026); scenario-based, subject to regulatory and issuer disclosures. Not a transaction recommendation.
INSTITUTIONAL INVESTMENT RESEARCH | NOT INVESTMENT ADVICE
01 | EXECUTIVE ASSESSMENT
Profitability outlook: resilience with a margin constraint
H1 earnings establish a strong starting point, but the full-year trajectory is more sensitive to regulatory spread repricing and treasury returns than to moderate equity-index appreciation.
Research stance — HOLD / NEUTRAL. At the 8 October 2026 Tk 66.40 reference, BRAC Bank has undemanding forward earnings multiples but material earnings-normalisation and bank-specific execution risks. 2026E profits increase from FY2025; 2027–2028 growth is modest in the central case as spread regulation, provisions and operating costs absorb balance-sheet growth. This is a conditional non-personal research categorisation, not a transaction instruction.
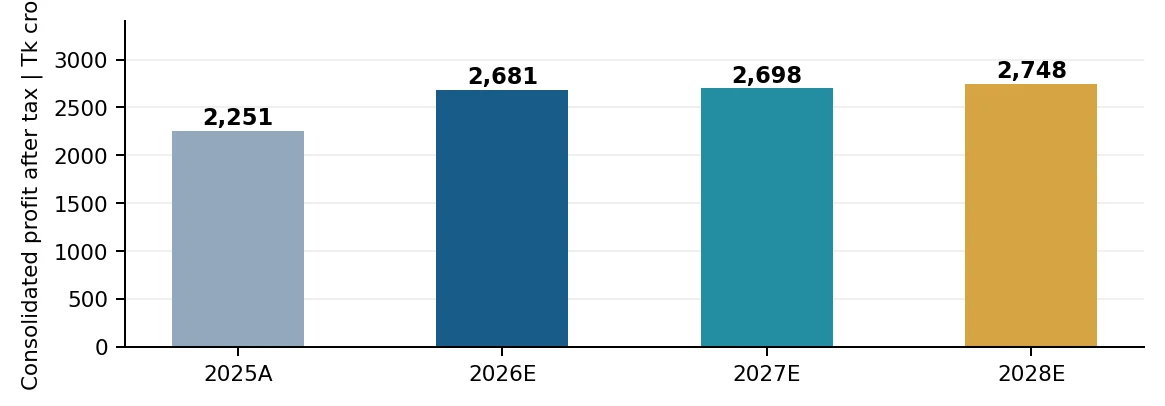
Metric | FY2025A* | 2026E | 2027E | 2028E |
Consolidated PAT (Tk Cr) | 2,251 | 2,681 | 2,698 | 2,748 |
Group PAT growth | — | +19.1% | +0.6% | +1.9% |
Attributable EPS (Tk) | 7.93** | 9.55 | 9.66 | 9.89 |
End-year loans (Tk Cr) | 73,141 | 83,000 | 94,000 | 105,000 |
End-year deposits (Tk Cr) | 99,036 | 118,000 | 131,500 | 146,000 |
*FY2025 PAT and share-adjusted EPS are from the earlier Empire Capital note, not independently reconstructed here from the full FY2025 signed accounts. **FY2025 EPS Tk 7.93 reflects the cited 15% bonus-share adjustment. All E columns are Empire Capital scenario estimates.
Decision-relevant risks
- 4pp ceiling applies to the regulatory weighted-average spread on eligible loans, not to group NIM or bKash income.
- bKash Digital Bank received initial selection / LoI pathway; ownership and related-party arrangements remain unverified, so zero incremental digital-bank profit is included.
- Stock-index appreciation is a separate scenario driver for assumed securities-market fee income, not an automatic increase in all brokerage or investment income.
01A | RESEARCH RATING
HOLD / NEUTRAL — balanced risk–reward, limited near-term earnings acceleration
Non-personal analytical assessment | 12–18-month horizon | Price reference: Tk 66.40, 8 October 2026. No assured target price.
Research rating | Reference valuation | Forecast signal |
HOLD / NEUTRAL | 2026E P/E 6.95x; 2027E P/E 6.87x | 2027E group PAT +0.6% YoY |
Moderate conviction; high model uncertainty | H1 2026 P/B 1.34x | 2028E group PAT +1.9% YoY |
Why not a more positive rating. The lower forward P/E is constructive, but a 4-percentage-point cap on the eligible weighted-average loan/deposit spread, strong dependence on investment/treasury income, and modest projected 2027–2028 PAT expansion impair the evidence for near-term EPS re-rating. The post-cap issuer-specific pricing bridge has not been disclosed.
Why not a negative rating. H1 2026 group earnings increased 57% YoY, reported standalone NPL was 2.03%, NPL coverage was 145%, and bKash remains a meaningful operating asset. Consolidated EPS is projected to remain positive throughout the FY2026–FY2028 scenario horizon, even though model outcomes are sensitive to assumptions.
2027E illustrative valuation band — multiple…
Continue reading the full analysis
The remaining research is delivered only after server-side access verification and is not included in this page response.