Market movement, placed in context.
Periodic market, industry, policy and global-cue updates for decision-makers who need more than the closing number.
Today's market context
The newest update from Empire Capital's market intelligence desk.
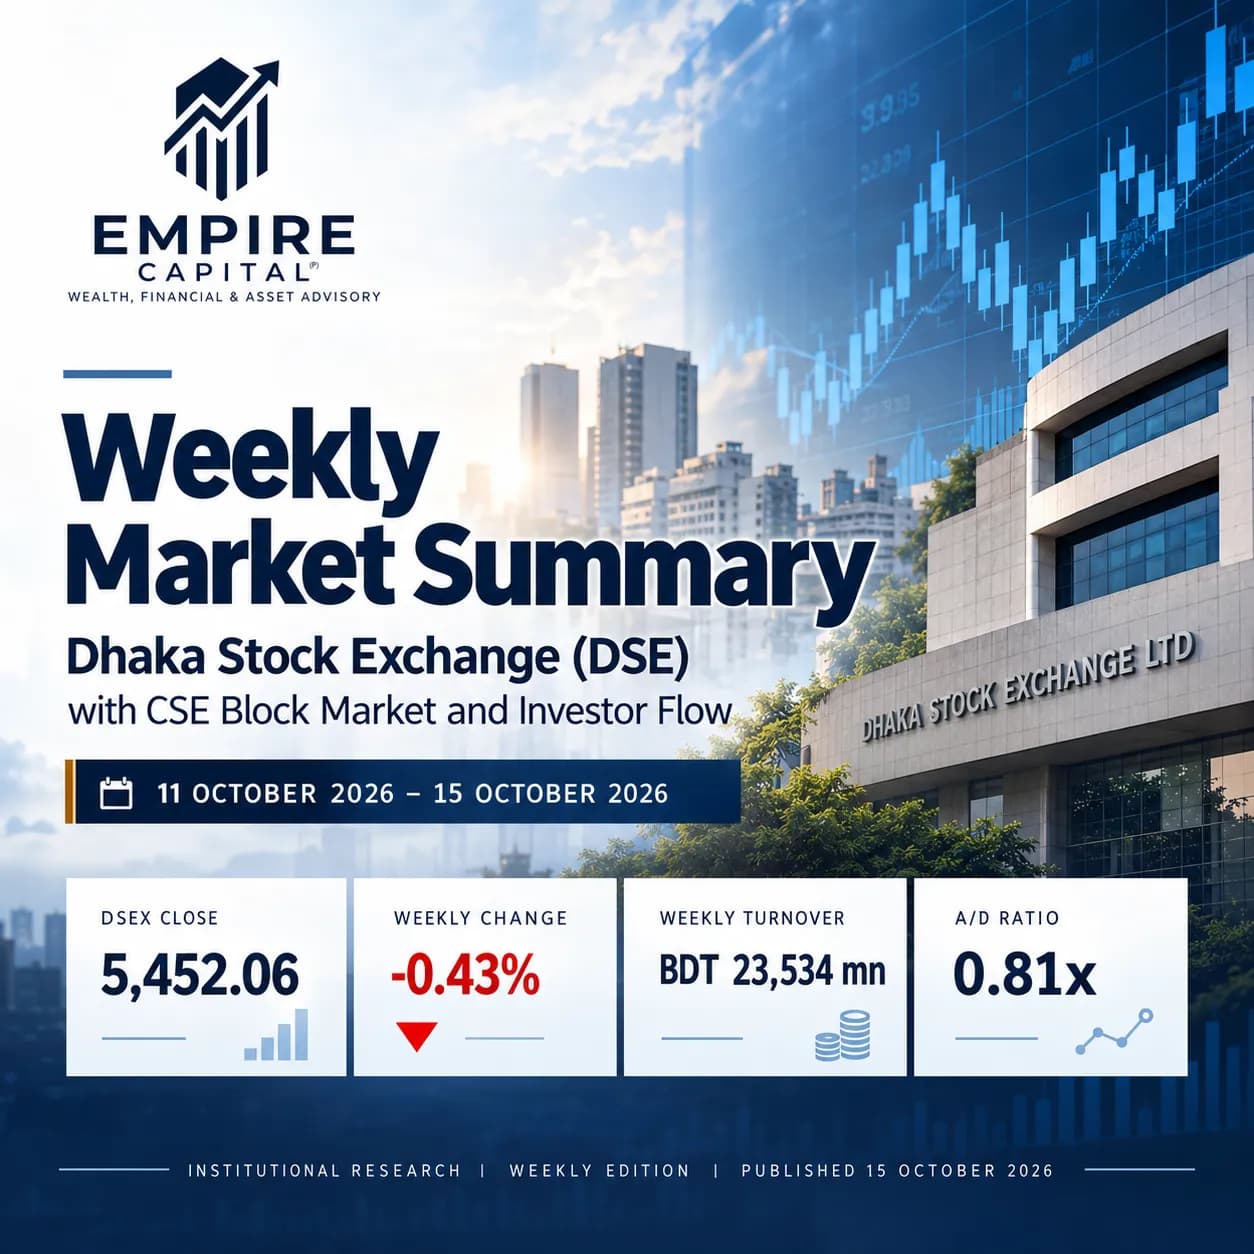
DSEX Ends Third Consecutive Week Lower Despite Strong Late-Week Breadth Recovery
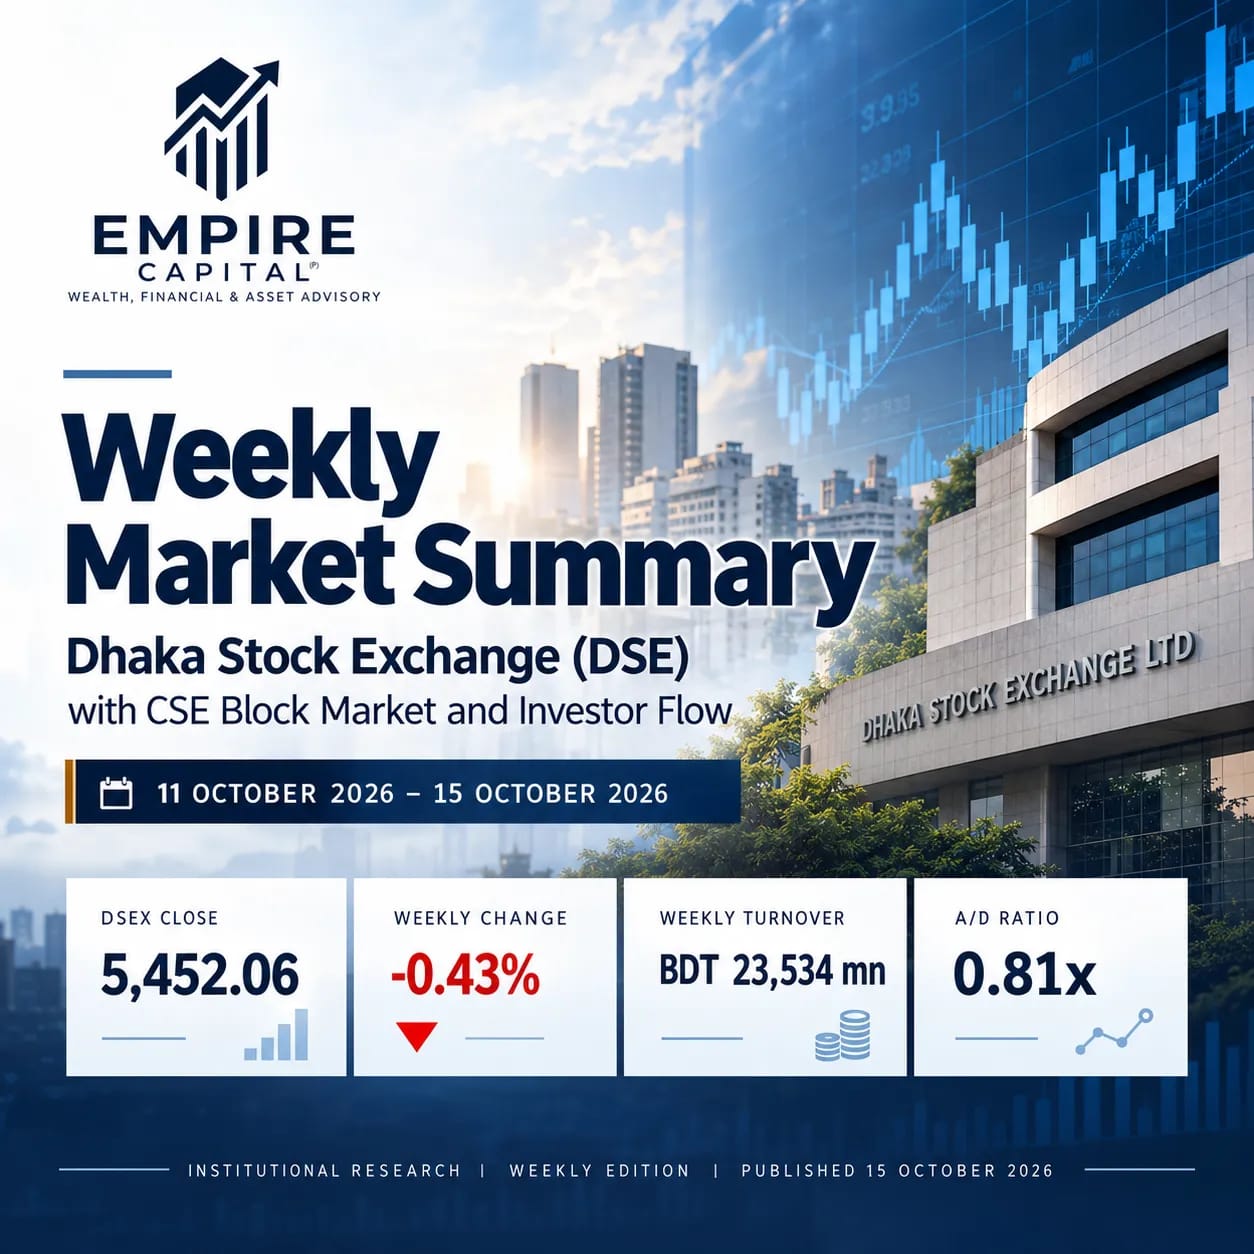
DSEX closed the week at 5,452.06, down 0.43%, marking a third consecutive weekly decline. After falling to 5,404.87 on 12 October, the index recovered across the final three sessions as breadth strengthened sharply, with the A/D ratio reaching 2.67x on 15 October. However, weekly turnover declined 15.42% to BDT 23.53 billion, keeping liquidity subdued despite improving market participation.
Read the updateRecent market updates
Bangladesh Capital Market Daily Trading Summary | 15 October 2026
Bangladesh’s stock market gained momentum on 15 October 2026, with the DSEX rising 0.42% to close at 5,452.06 points, marking its third consecutive session of gains. Dhaka Stock Exchange turnover increased 20.07% to Tk 4.997 billion, while market breadth strengthened significantly, with 247 advancing issues against 95 decliners. The Chittagong Stock Exchange also showed signs of recovery, with the provisional CSCX rising 0.50%. Empire Capital Research examines the improving market sentiment, sector rotation, trading liquidity, technical indicators and key support and resistance levels to assess whether the rebound can develop into a more sustainable recovery.
DSEX Extends Stabilization as Breadth Broadens, but Recovery Trigger Remains Unmet and CSE Breaks Key Support
Bangladesh’s equity market remained mixed on 14 October 2026. DSEX rose 0.38% to 5,429.37, with DS30 and DSES also positive. Breadth stayed constructive at 206 advances versus 141 declines, while regular-market turnover increased 2.64% despite flat headline turnover. The recovery remained unconfirmed as DSEX failed to close above the 5,441.91 recovery trigger and stayed below its 5-, 10- and 20-day moving averages. RSI improved to 37.73, but turnover remained 19.21% below the five-day average. Meanwhile, CSCX fell 0.14% to 8,904.57, slipping below its 14 September low. However, with CSE turnover at only Tk 65.30 million, the move is viewed as a low-turnover downside break rather than a confirmed breakdown.
Bangladesh Capital Market Daily Trading Summary : 13 October 2026
Bangladesh’s equity market showed tentative stabilisation on 13 October 2026, with the DSEX edging 0.07% higher to 5,408.90 after the previous session’s 0.85% decline. Market breadth improved sharply to 201 advances against 144 declines, producing an A/D ratio of 1.40x, while all 30 traded mutual-fund units advanced. However, the improvement was not supported by liquidity: DSE turnover fell 8.11% to Tk 4,161.05 million, transactions declined 13.99%, and regular-market turnover excluding blocks dropped 14.66% to Tk 3,773.70 million. Large-cap participation remained weak, with DS30 falling 0.24% and DSES declining 0.05%. Block activity increased materially, accounting for 9.31% of DSE turnover, with SQURPHARMA alone contributing Tk 141.72 million. The broader technical picture remained cautious: DSEX held above immediate support at 5,402.15 but failed to retain its intraday move to 5,441.91, while turnover remained below its trailing benchmark. The report therefore classifies the session as a tentative, low-participation stabilisation rather than a technically confirmed recovery. On the CSE, CSCX fell 0.32% to 8,917.44, only 0.10% above the 14 September closing low of 8,908.96. CSE liquidity remained thin and concentrated, while its RSI eased to 34.44 and the MACD histogram narrowed to +0.33, leaving the exchange close to an important technical support test.
DSEX Reverses Lower as Rebound Fails at Resistance and Broad Selling Returns on Higher Activity
Bangladesh’s equity market reversed lower on 11 October 2026, ending the two-session rebound. The DSEX declined 0.45% to 5,451.04 and closed at the session low after reaching an intraday high of 5,496.94, indicating renewed selling pressure after another failure around the 5,482–5,510 resistance zone. Market breadth deteriorated sharply to 79 advances against 264 declines, while the DSE sentiment gauge dropped from 45 to 20, returning to “Extreme Bear.” Unlike the preceding rebound sessions, the decline occurred alongside stronger market activity. DSE turnover rose 6.64% to Tk 5,685.97 million, transactions increased 6.72%, and volume advanced 8.18%, suggesting active selling rather than simply weak participation. Large caps remained relatively defensive, with DS30 falling only 0.11%, while DSES declined 0.61% and DSMEX dropped 1.18%. Mutual funds and insurers were among the weakest segments, while retail investors turned marginal net sellers and institutions remained small net buyers. Technically, the failed rebound has returned attention to the 6 October support zone around 5,421.69–5,424.91, followed by the 14 September correction low of 5,379. The DSEX remains well below its recent rebound high and has retraced 71.5% of the 14–24 September recovery, leaving the short-term downtrend intact unless resistance is decisively reclaimed.
DSEX Falls 0.85% as Breadth Deteriorates and Liquidity Contracts, While Institutions Turn Net Buyers
Bangladesh’s capital market weakened further on 12 October 2026, with both exchanges closing lower. The DSEX fell 46.17 points, or 0.85%, to 5,404.87, while DSE turnover contracted 20.36% to Tk 4,528.11 million. Market breadth deteriorated sharply, with 300 declines against only 46 advances, producing an advance/decline ratio of just 0.15. The CSE also declined, with CSCX falling 0.66% to 8,939.68. Although CSE turnover rose strongly to Tk 290.42 million, the increase was concentrated in block trades and a small number of high-value public-board transactions rather than broad participation. The DSE decline came alongside lower turnover, volume and transactions, indicating thinner demand rather than capitulation. Market sentiment weakened further to 13/100, “Extreme Bear,” while 78.74% of DSE main-board issues declined. Sector activity was led by Textile, Insurance and Engineering, which together accounted for 46.74% of DSE turnover. Investor-flow estimates showed retail investors as net sellers, while institutions emerged as the largest estimated net buyers at Tk 84.41 million and foreign investors recorded a modest positive flow. Technically, DSEX closed below its 6 October level and established a new low within the five-session verified window. Immediate support is now around the 12 October intraday low of 5,402.15, while resistance lies around 5,424.91–5,451.04, followed by the stronger recovery zone around 5,475.58–5,496.94.
Market Update
Daily, weekly, monthly and quarterly market views with structure, breadth, liquidity and context.
Open desk 02Industry Updates
The operating and policy developments reshaping sector earnings, risk and opportunity.
Open desk 03Policy Update
Clear interpretation of market, regulatory and economic policy developments.
Open desk 04Global Market Cues
The external rates, currencies, commodities and risk signals most relevant to Bangladesh.
Open desk