October was a month of controlled retreat rather than panic. DSEX fell 2.40% to 5,417.44, marking a second consecutive monthly loss, while average daily turnover dropped 24.90% to Tk489.20 crore. Large caps proved more resilient, with DS30 down only 1.02%, while DSES fell 4.70% and the median stock declined 6.32%. The index tested September’s critical 5,379 support but did not close below it.
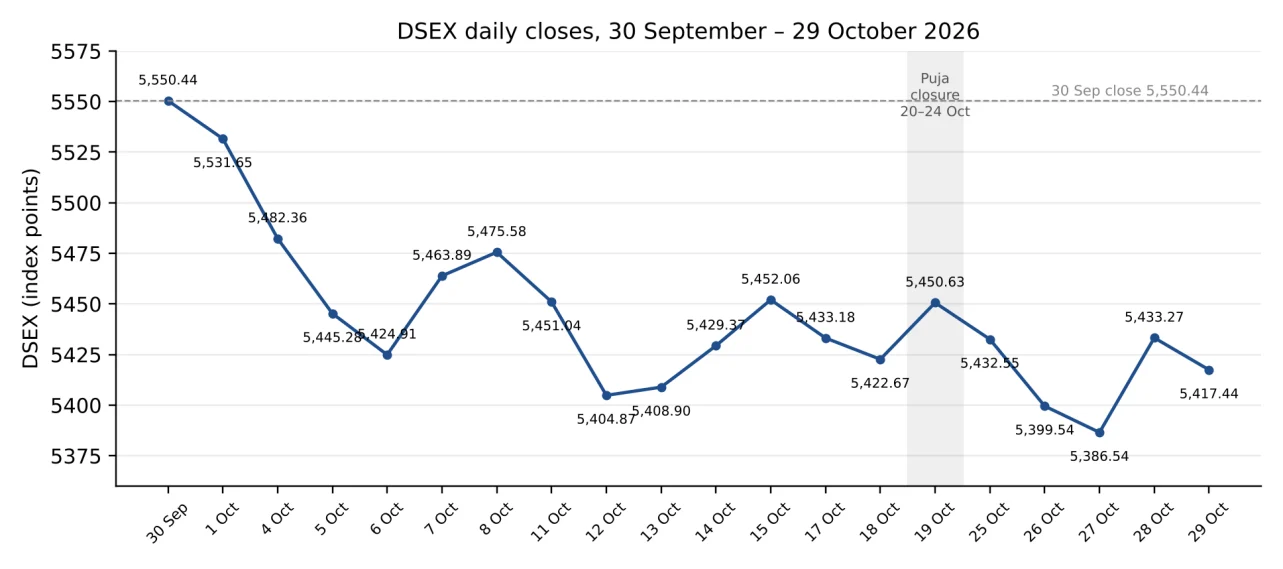
Figure 1. DSEX daily closes, 30 September–29 October 2026 (19 sessions). DSE and CSE were closed 20–24 October for Durga Puja.
1. Executive Summary
October was a month of retreat on thinning liquidity, set against a renewed oil shock and the first test of the June year-end results season. The DSEX fell 2.40% (-133.00 points) to 5,417.44, its second consecutive monthly loss, leaving the index 11.35% higher year-to-date (14.08% at end-September). The decline was gradual rather than disorderly: 12 of 19 sessions closed lower, daily volatility was 0.50% (7.8% annualised, against 13.3% in September) and no session moved more than 0.89%. The DS30 lost only 1.02% while the DSES fell 4.70%, and the median stock fell 6.32%: capital concentrated in large, liquid names while small and mid-caps were sold. The index tested but did not close below September's 5,379.00 low, reaching 5,386.54 on 27 October (intraday 5,378.87) before a broad 0.87% rebound on 28 October.
Four forces shaped the month. Oil and Iran: Brent futures rose from $100.32 on 5 October to a $116.72 settlement on 23 October as tanker attacks around Hormuz and Houthi strikes on Saudi infrastructure escalated, crossing the $105 threshold of our Scenario 3. Power: national unserved electricity fell from 7.46% of demand in 1–7 October to 2.06% in 22–28 October, but the grid relied on Tk20.6/kWh furnace-oil generation and record imports. Rates: the US 10-year yield touched 5.31% on 5 October and the Fed held at 3.75%–4.00% on 28 October. Earnings: of 45 FY26 declarations captured in October, nine paid high cash dividends (30% or more) and nine paid nothing; the market rewarded quality sharply, with high-dividend payers flat (median -0.38%) and no-dividend companies down a median 10.20%. Turnover averaged Tk489.20 crore (-24.90%), foreign investors were implied net sellers of Tk149.16 crore, and at the CSE CASPI fell 1.92%. For Empire Capital, conditions have moved from Scenario 2 to the S2–S3 boundary: the energy trigger for S3 has been hit, but the DSEX has so far held the support that separates the two.
2. October at a Glance
Metric | September 2026 | October 2026 | Change | Assessment |
|---|---|---|---|---|
DSEX (close) | 5,550.44 | 5,417.44 | -2.40% | Second monthly loss |
DSEX year-to-date | +14.08% | +11.35% | -2.73 pp | Gains still substantial |
DS30 (close) | 2,108.45 | 2,086.86 | -1.02% | Large caps most resilient |
DSES (close) | 1,102.49 | 1,050.67 | -4.70% | Weakest index again |
Average daily turnover | Tk651.39cr (22) | Tk489.20cr (19) | -24.90% | Liquidity contraction |
Highest / lowest session | Tk844.70cr / Tk486.55cr | Tk723.11cr / Tk317.38cr | -14.39% / | Highest: |
Total turnover | Tk14,330.54cr | Tk9,294.80cr | -35.14% | Tk 486.55cr → Tk 317.38cr; down Tk 169.17cr |
Trades per session (avg) | 181,943 | 157,605 | -13.38% | Fewer participants |
Volume per session (avg) | 226.54mn | 170.47mn | -24.75% | Lower share turnover |
Market capitalisation | Tk687,477cr | Tk674,476cr | -1.89% | 29 Oct official |
Advance/decline (month) | 3,177 / 3,981 (0.80) | 2,248 / 3,774 (0.60) | -0.20 | Breadth weaker |
Median stock return | -2.10% | -6.32% | -4.22 pp | Broad-based decline |
Market P/E | 8.82x | 8.62x | -0.20x | Valuation lower |
CSE CASPI (close) | 14,814.69 | 14,529.95 | -1.92% | To 28 Oct |
CSE avg daily turnover | Tk25.05cr | Tk17.03cr | -32.00% | 18 sessions to 28 Oct |
Combined block turnover | Tk970.43cr | Tk677.59cr | -30.18% | DSE 88.46% |
Implied foreign net flow | -Tk53.74cr (21) | -Tk149.16cr (18) | -Tk. 95.42 cr | Net selling increased from Tk 53.74cr to Tk 149.16cr |
Brent (settlement) | ~$103 (21 Sep) | $115.32 (28 Oct) | Approximately +11.96% | High $116.72 (23 Oct) |
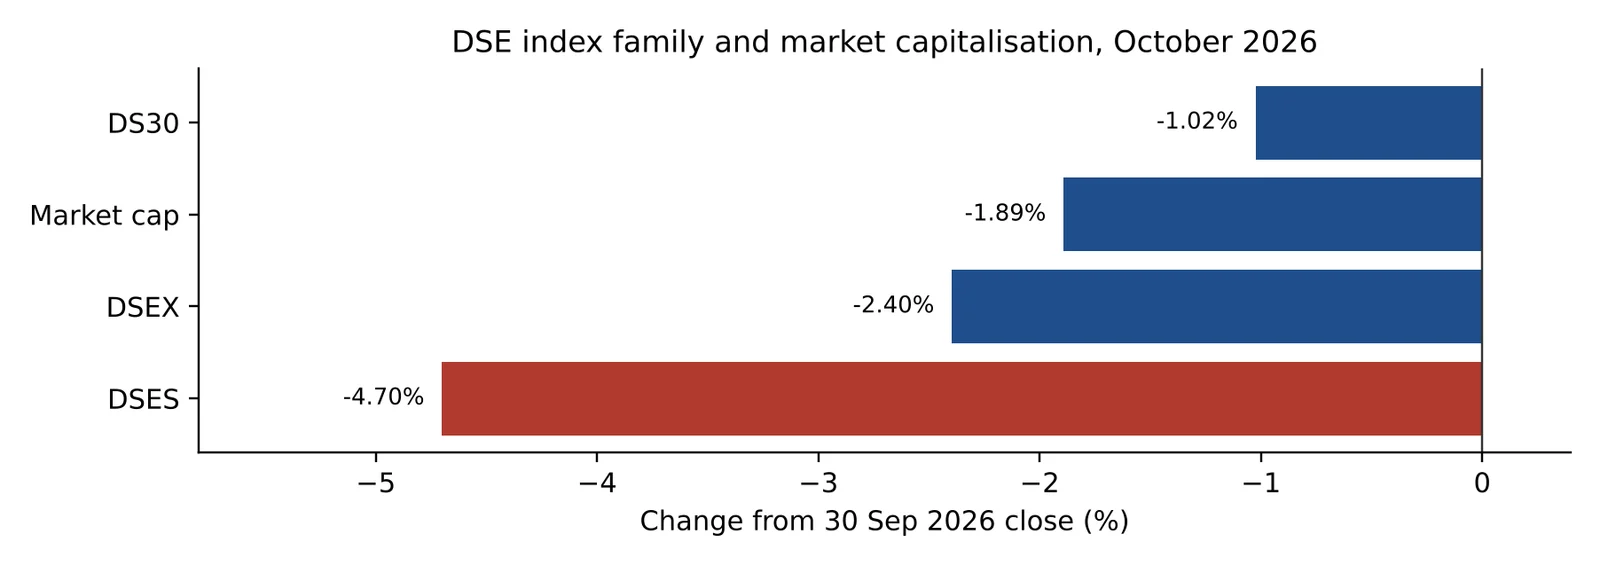
Figure 2. DSE index family and market capitalization, 30 September–29 October 2026.
3. Energy: Iran–Oil Shock and the Power System
September's relief proved temporary. Gulf crude exports had recovered strongly in September (IEA: 13.9 mb/d, above 75% of pre-war levels), but October tanker attacks, security constraints and freight costs threatened that progress. Reuters-reported Brent settlements rose from $100.32 on 5 October to $104.72 on 9 October, $106.06 on 14 October, $109.55 on 19 October and $116.72 on 23 October (+16.35% from 5 October), the strongest settlement in the sample, before easing to $113.88 on 27 October on Saudi, Turkish, Pakistani and Qatari diplomacy in Tehran and recovering to $115.32 on 28 October after a reported Houthi strike on a 550,000 b/d Saudi refinery. On 29 October Brent traded at $114.47 (intraday) as renewed US–Iran diplomacy was reported.
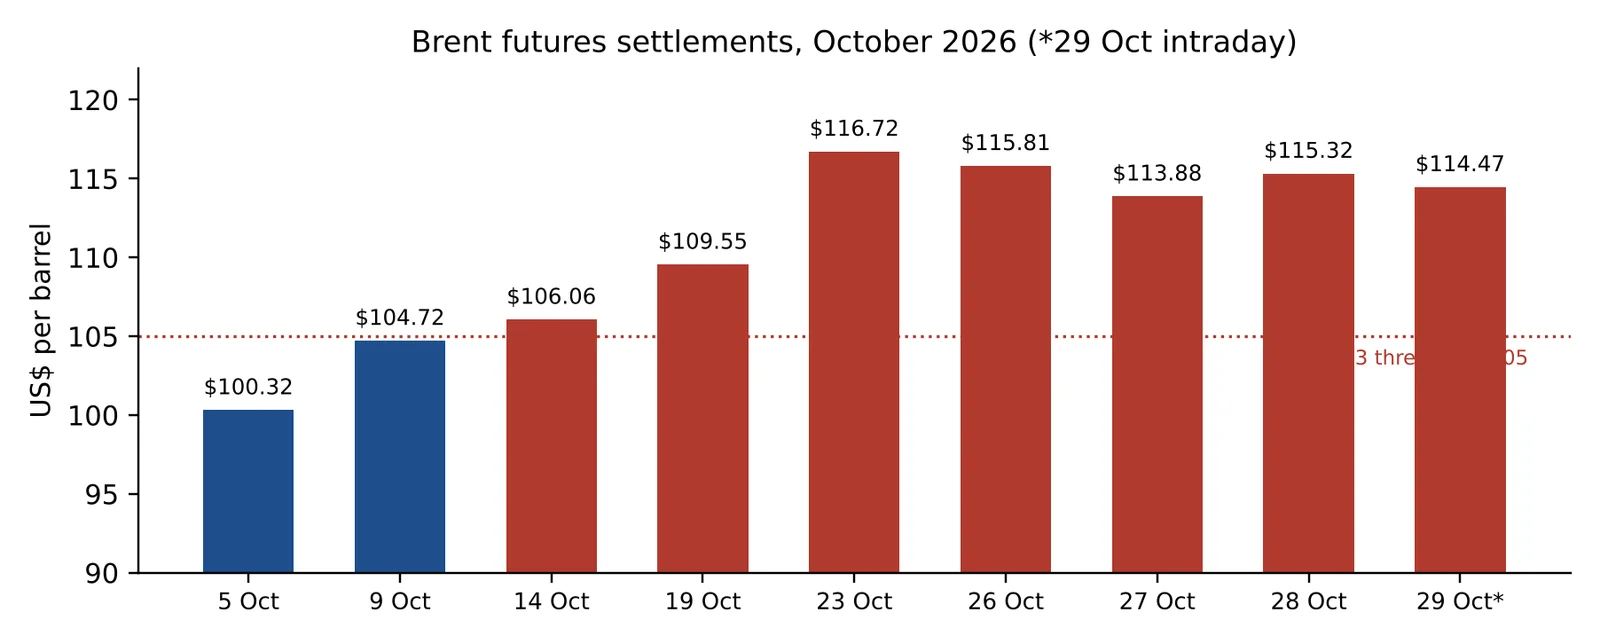
Figure 3. Selected Reuters-reported Brent futures settlements (US$/bbl); the 29 October point is a 07:20 UTC intraday quotation, not a settlement. Bars at or above the $105 Scenario 3 threshold in red.
Iran–oil chronology, October 2026 | ||
Date(s) | Development | Evidence |
1–5 Oct | Tankers Kazimah III (1 Oct) and Lipsi (4 Oct) reportedly struck; seven OPEC+ members kept November required production unchanged (4 Oct). | Reuters; OPEC |
7–9 Oct | 12 tanker incidents reported in 28 Sep–5 Oct, the most of any week since the war began; oil rose 4% on 8 Oct with Hurricane Isaias; US–Iran signals eased prices on 9 Oct. | Reuters |
13–16 Oct | Vortexa: US blockade kept Iranian seaborne crude exports at zero; IEA reported persistent refined-product deficit; VLCC freight eased from record (WS 841 to 776). | Reuters; IEA |
19–23 Oct | Threats extended to the Gulf of Oman; Houthis claimed attacks on Saudi sites; Brent settled $116.72 on 23 Oct. | Reuters |
26–29 Oct | Diplomacy in Tehran and Qatari mediation; reported Houthi strike on a Saudi refinery (unconfirmed); Brent $115.32 on 28 Oct, $114.47 intraday on 29 Oct. | Reuters |
Attack claims are treated as claims unless independently verified; a reported attack does not establish a confirmed production shutdown.
The constraint is products, not only crude. The IEA reported Middle East refined-product exports of 1.9 mb/d in September (40.43% of the pre-war 4.7 mb/d) and LPG exports of 0.67 mb/d (44.67% of 1.50 mb/d), observed…
Continue reading the full analysis
The remaining research is delivered only after server-side access verification and is not included in this page response.