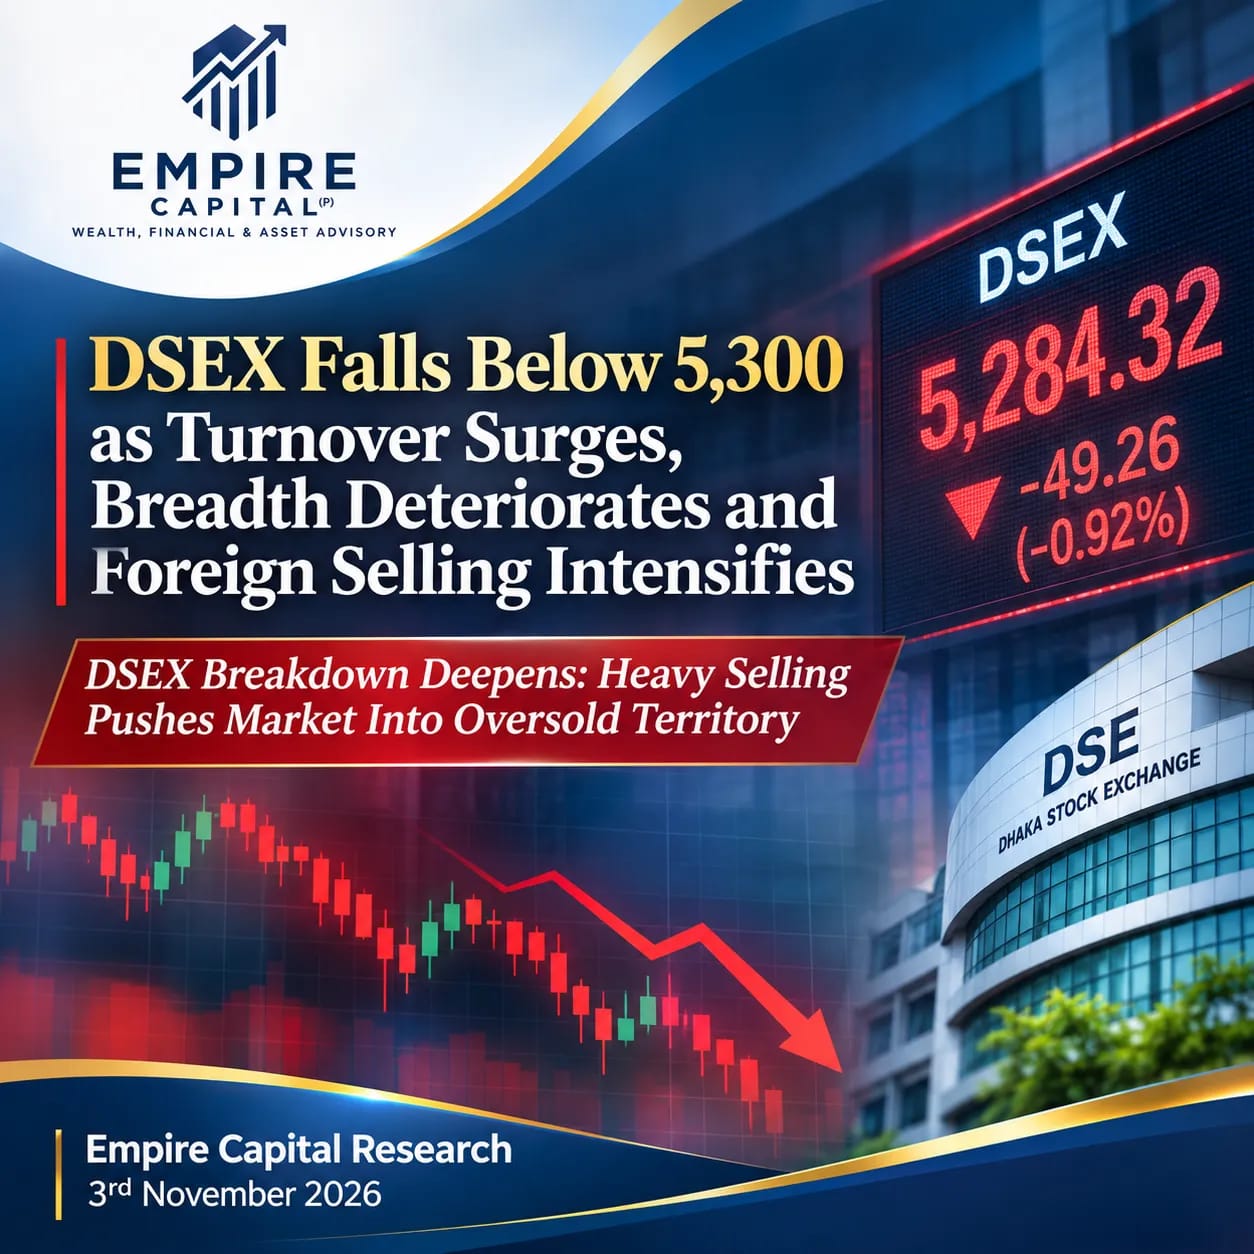
DSEX fell 0.92% to 5,284.32 on 3 November, extending its decline for a third consecutive session. Selling intensified as turnover surged 35.29% to Tk 5,658.27 million and breadth weakened to 68 advances versus 266 declines. RSI dropped to 29.40, entering oversold territory, while the MACD histogram widened to −6.91, confirming stronger downside momentum.
1. Executive Market Summary
The DSEX extended its breakdown on Tuesday, 3 November 2026, falling 49.26 points (-0.92%) to 5,284.32, a third straight decline. All four DSE indices fell: DS30 -0.99%, DSES -0.72% and CDSET -0.98%. The index opened near its high of 5,356.77, slid to a low of 5,269.87 in the early afternoon, rallied to about 5,302 shortly before the close, then fell back to 5,284.32 on the closing print. It is now 94.68 points below the 14 Sep correction low and 148.95 points below the 28 Oct rebound high close.
Unlike 2 Nov, selling came on heavier participation. Turnover rose 35.29% to Tk 5,658.27 mn, regular-board value 30.48% to Tk 5,346.54 mn, and transactions 9.92% to 180,745. Blocks were 5.46% of turnover. Breadth weakened further to 68 advances, 266 declines and 50 unchanged (A/D 0.26x), the weakest since 25 Oct. Mutual funds fell 21 to 1 for a second session.
On the CSE, CSCX fell 1.38% to 8,727.71 and CASPI 1.22% to 14,214.71 against official 2 Nov closes; CSE50 (−1.74%) and CSE30 (−1.65%) fell hardest. CSE turnover fell 21.63% to Tk 127.15 mn, with CITYGENINS again the largest name (Tk 39.26 mn).
KEY OBSERVATION | The breakdown is accelerating and broadening. Most of the market fell, but money concentrated in a handful of textile names, ENVOYTEX (+9.54%, Tk 360.31 mn), MATINSPINN (+8.95%, Tk 287.18 mn) and HWAWELLTEX (+9.96%), which kept Textile value at Tk 1,777.2 mn. DSEX RSI fell to 29.40, below 30 and into oversold territory, and the MACD histogram widened to -6.91. The terminal sentiment gauge read 18 'Extreme Bear' (2 Nov: 22).
SCENARIO CASTING | The 3 Nov close confirms that the breakdown is extending on heavier value. Both the extension and the higher-participation selling conditions set on 2 Nov were met. The next session (Wednesday, 4 November) needs to show whether oversold momentum produces a pause or the decline continues. All levels come from today's report.
- Failed breakdown: not met: The DSEX high (5,356.77) stayed below 5,368.42 and 5,379.00.
- Stabilisation (base case): not met: The DSEX closed below 5,333.58 (2 Nov low).
- Extension: met: Close 5,284.32, below 5,333.58, with A/D 0.26x (below 0.50x).
- Higher-participation selling: met: Regular-board value was Tk 5,346.54 mn, above the Tk 4,600 mn threshold.
Table 1A: Scenarios for the next session
Scenario | Trigger | What it means |
|---|---|---|
Oversold rebound | DSEX closes above 5,333.58 (2 Nov close), with A/D above 1.00x | A relief rally inside a downtrend; 5,356.77 and 5,370.75 (5-SMA) come next |
Pause (base case) | DSEX holds above 5,269.87 (today's low), A/D 0.50–1.00x | Selling eases from oversold levels without a reversal |
Continuation | Close below 5,269.87 with A/D below 0.50x | The decline extends; no lower reference level exists in the supplied reports |
Capitulation | Close below 5,269.87 with regular-board turnover above Tk 5,300 mn | High-volume liquidation; often precedes exhaustion, but not a signal on its own |
Momentum markers | RSI is 29.40, below 30 and oversold for the first time in this series. Oversold readings can persist in a falling market; a move back above 30 with improving breadth…
Continue reading the full analysis
The remaining research is delivered only after server-side access verification and is not included in this page response.